In simplest terms, a mortgage is a long-term loan designed to help borrowers purchase a house. It allows individuals to become homeowners without making a large down payment and thus fulfilling the American Dream. Once you become a homeowner, a mortgage represents one of your life's biggest financial commitments. So it's important to understand the structure of your payments - what percentage goes to principal, interest, and taxes, and what you currently owe on your loan balance.
I'm a First-Time Home Buyer. Once I Closed on My New Home, When Will My Mortgage Payment Start?
Mortgage payments usually start one full month after the last day of the month in which the home purchase closed. Unlike rent payments, which are usually paid in advance on the first day of the month, mortgage payments are paid in arrears. This means the payment is expected to be made at the end of the month. For instance, after closing on your new home on March 28, the first full mortgage payment, which is for April, is then due on May 1.
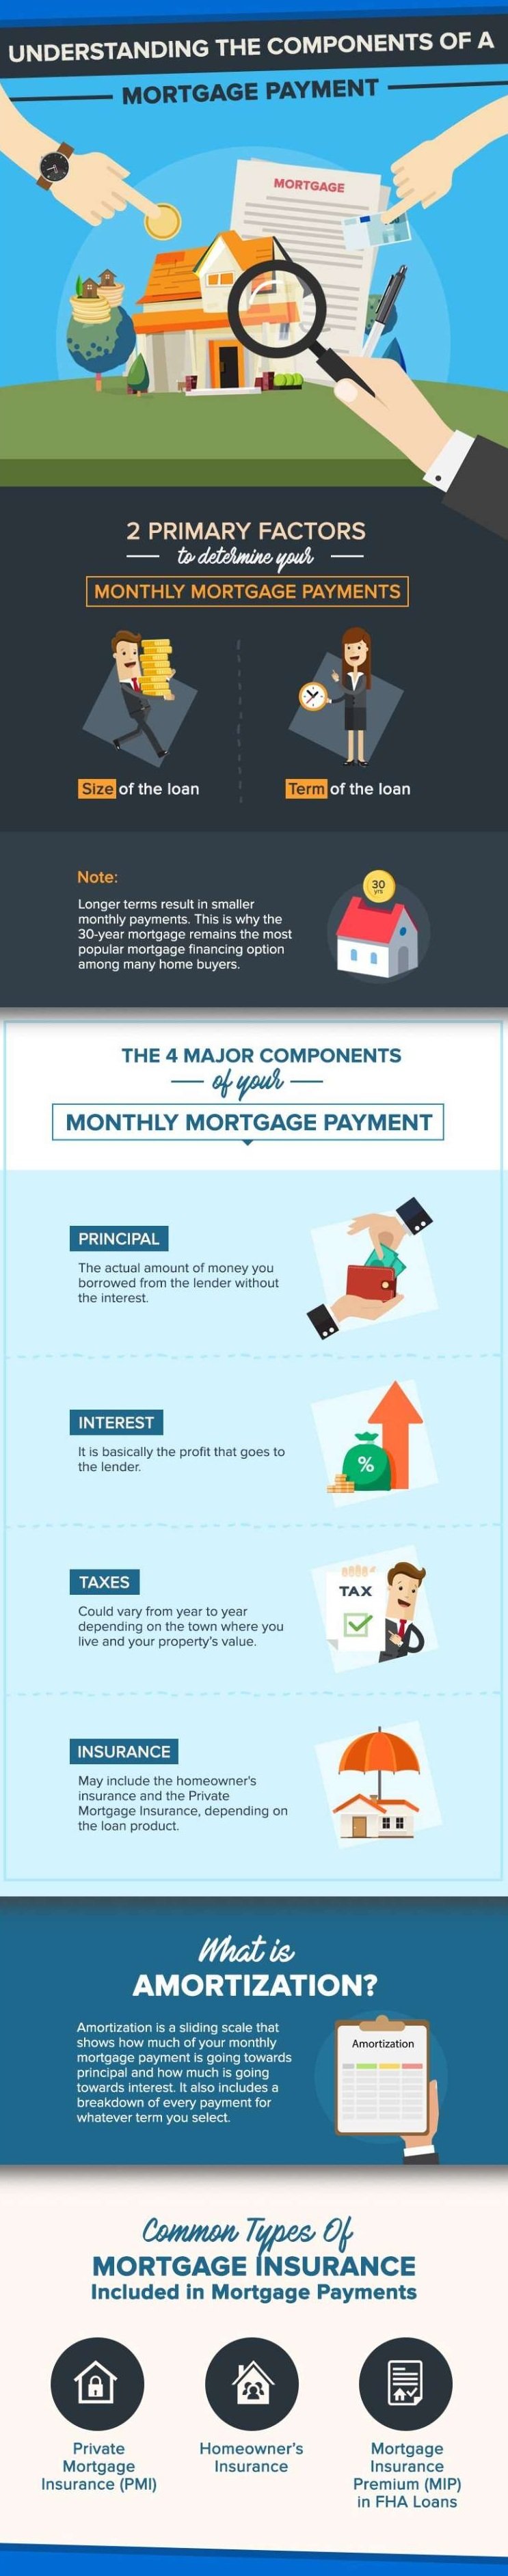
2 Primary Factors to Determine Your Monthly Mortgage Payments
- Size of the loan - refers to the amount of money borrowed.
- Term of the loan - the length of time within which the loan must be fully paid back.
Remember: Longer terms result in smaller monthly payments. This is why the 30-year mortgage remains the most popular mortgage financing option among many home buyers.
Remember PITI: The 4 Major Components of a Mortgage Payment
PRINCIPAL
The actual amount of money you borrowed from the lender without the interest. It is the face value of your mortgage on the first day. For instance, if your mortgage is $250,000 with a 4.5% interest rate, your principal remains at $250,000.
A portion of each mortgage payment goes to the repayment of the principal. If you take a mortgage with a fixed interest rate, your principal repayment will be the same for the life of the loan. A greater amount of the principal is paid during the back half of the loan because the majority of the payment in the first few years goes primarily to interest.
To calculate your starting principal balance:
Principal Balance = Purchase Price + Fees Rolled into Mortgage - Down payment
INTEREST
The interest is another big part of your mortgage payment. It is basically the profit that goes to the lender.
Think of it as the lender's reward for taking a risk and lending money to a borrower. Lenders will want to earn their interest back in the first few years of the loan repayment before they start reducing principal. Meaning, the majority of your mortgage payment goes to the interest in those first few years, but every month you pay down a little bit of principal as well. This is the method banks use to protect themselves in the event of a default. But the more payments you make, the less goes to interest and a bit more goes to the principal. For a 30-year loan, the first seven years will go mostly towards the interest.
Higher interest rates mean higher mortgage payments
Interest is accrued annually regardless of whether you have a fixed-rate mortgage or an adjustable-rate mortgage. It's important to note that the interest rate on a mortgage has a direct impact on the size of a mortgage payment. The average 30-year fixed-mortgage rate until March this year is 4.54%, which rose slightly since November 2017.
To calculate how much of your payment goes to interest: Interest Portion = Current Principal Balance x (APR = 12)
Side Note: What is amortization?
Amortization is a sliding scale that shows how much of your monthly mortgage payment is going towards
principal and how much is going towards interest. It also includes a breakdown of every payment for whatever term you select. To have an idea of where your monthly payment typically goes, visit your lender's website and print off a copy of your amortization schedule. There are also free amortization schedule calculators online that you can use as a guide to estimate the monthly payment on your mortgage.
TAXES
Almost all lenders require you to include, or escrow, the taxes into your monthly payment. This is because property taxes take priority over everything else. The tax portion of your payment could vary from year
to year depending on the town where you live and your property's value. Real estate taxes are assessed by governmental agencies and used to fund various public services, including the school district, road construction, the police and fire department services, and others.